Total 365 Questions |
Updated On: Oct 27, 2026
Start Your Succesful IT Certification Journey With 3 Easy Steps!
1
GET ACCESS / DOWNLOAD
- Get Full Access to Practice Features
- Download Real PDF Questions
- Download Free Demo Version
- Download Free Updated (90 Days)
2
ONLINE PRACTICE
- Free Online IT Exam Practice
- Multiple Questions Sets
- Browser Based Test Engine
- No Installation Required
3
PASS / SUCCESS
- Pass Exam Efficiently
- Achieve A+ Grade
- Guaranteed Success
- Start Brilliant Pro Career
Free CFA Institute CFA-Level-III Exam Questions
Become CFA Institute Certified with updated CFA-Level-III exam questions and correct answers
Page: 1
/ 73
Question 1
Jack Mercer and June Seagram are investment advisors for Northern Advisors. Mercer graduated from aprestigious university in London eight years ago, whereas Seagram is newly graduated from a mid-westernuniversity in the United States. Northern provides investment advice for pension funds, foundations,endowments, and trusts. As part of their services, they evaluate the performance of outside portfolio managers.They are currently scrutinizing the performance of several portfolio managers who work for the ThompsonUniversity endowment.Over the most recent month, the record of the largest manager. Bison Management, is as follows. On March 1,the endowment account with Bison stood at $ 11,200,000. On March 16, the university contributed $4,000,000that they received from a wealthy alumnus. After receiving that contribution, the account was valued at $17,800,000. On March 31, the account was valued at $16,100,000. Using this information, Mercer andSeagram calculated the time-weighted and money-weighted returns for Bison during March. Mercer states thatthe advantage of the time-weighted return is that it is easy to calculate and administer. Seagram states that themoney-weighted return is, however, a better measure of the manager's performance.Mercer and Seagram are also evaluating the performance of Lunar Management. Risk and return data for themost recent fiscal year are shown below for both Bison and Lunar. The minimum acceptable return (MAR) forThompson is the 4.5% spending rate on the endowment, which the endowment has determined using ageometric spending rule. The T-bill return over the same fiscal year was 3.5%. The return on the MSCI WorldIndex was used as the market index. The World index had a return of 9% in dollar terms with a standarddeviation of 23% and a beta of 1.0. The next day at lunch, Mercer and Seagram discuss alternatives for benchmarks in assessing the performanceof managers. The alternatives discussed that day are manager universes, broad market indices, style indices,factor models, and custom benchmarks. Mercer states that manager universes have the advantage of beingmeasurable but they are subject to survivor bias. Seagram states that manager universes possess only onequality of a valid benchmark.Mercer and Seagram also provide investment advice for a hedge fund, Jaguar Investors. Jaguar specializes inexploiting mispricing in equities and over-the-counter derivatives in emerging markets. They periodically engagein providing foreign currency hedges to small firms in emerging markets when deemed profitable. This mostcommonly occurs when no other provider of these contracts is available to these firms. Jaguar is selling a largeposition in Mexican pesos in the spot market. Furthermore, they have just provided a forward contract to a firmin Russia that allows that firm to sell Swiss francs for Russian rubles in 90 days. Jaguar has also entered into acurrency swap that allows a firm to receive Japanese yen in exchange for paying the Russian ruble.Regarding their statements about manager universes, determine whether Mercer and Seagram are correct orincorrect.
Answer: C
Question 2
Garrison Investments is a money management firm focusing on endowment management for small collegesand universities. Over the past 20 years, the firm has primarily invested in U.S. securities with small allocationsto high quality long-term foreign government bonds. Garrison's largest account, Point University, has a marketvalue of $800 million and an asset allocation as detailed in Figure 1.Figure 1: Point University Asset Allocation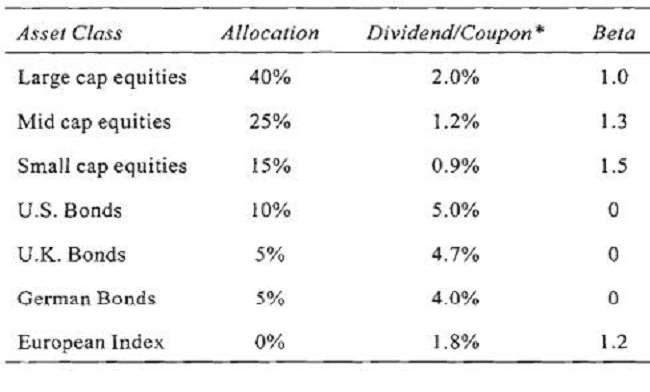 *Bond coupon payments are all semiannual.
Managers at Garrison are concerned that expectations for a strengthening U.S. dollar relative to the British
pound could negatively impact returns to Point University's U.K. bond allocation. Therefore, managers have
collected information on swap and exchange rates. Currently, the swap rates in the United States and the
United Kingdom are 4.9% and 5.3%, respectively. The spot exchange rate is 0.45 GBP/USD. The U.K. bonds
are currently trading at face value.
Garrison recently convinced the board of trustees at Point University that the endowment should allocate a
portion of the portfolio into international equities, specifically European equities. The board has agreed to the
plan but wants the allocation to international equities to be a short-term tactical move. Managers at Garrison
have put together the following proposal for the reallocation:
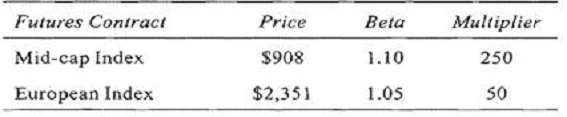
To minimize trading costs while gaining exposure to international equities, the portfolio can use futures
contracts on the domestic 12-month mid-cap equity index and on the 12-month European equity index. This
strategy will temporarily exchange $80 million of U.S. mid-cap exposure for European equity index exposure.
Relevant data on the futures contracts are provided in Figure 2.
Figure 2: Mid-cap index and European Index Futures Data
 Three months after proposing the international diversification plan, Garrison was able to persuade PointUniversity to make a direct short-term investment of $2 million in Haikuza Incorporated (HI), a Japaneseelectronics firm. HI exports its products primarily to the United States and Europe, selling only 30% of itsproduction in Japan. In order to control the costs of its production inputs, HI uses currency futures to mitigateexchange rate fluctuations associated with contractual gold purchases from Australia. In its current contract, HIhas one remaining purchase of Australian gold that will occur in nine months. The company has hedged thepurchase with a long 12-month futures contract on the Australian dollar (AUD).Managers at Garrison are expecting to sell the HI position in one year, but have become nervous about theimpact of an expected depreciation in the value of the Yen relative to the U.S. dollar. Thus, they have decidedto use a currency futures hedge. Analysts at Garrison have estimated that the covariance between the localcurrency returns on HI and changes in the USD/Yen spot rate is -0.184 and that the variance of changes in theUSD/Yen spot rate is 0.92.Which of the following best describes the minimum variance hedge ratio for Garrison's currency futures hedgeon the Haikuza investment?
Answer: A
Question 3
Joan Nicholson, CFA, and Kim Fluellen, CFA, sit on the risk management committee for Thomasville AssetManagement. Although Thomasville manages the majority of its investable assets, it also utilizes outside firmsfor special situations such as market neutral and convertible arbitrage strategies. Thomasville has hired ahedge fund, Boston Advisors, for both of these strategies. The managers for the Boston Advisors funds areFrank Amato, CFA, and Joseph Garvin, CFA. Amato uses a market neutral strategy and has generated a returnof S20 million this year on the $100 million Thomasville has invested with him. Garvin uses a convertiblearbitrage strategy and has lost $15 million this year on the $200 million Thomasville has invested with him, withmost of the loss coming in the last quarter of the year. Thomasville pays each outside manager an incentive feeof 20% on profits. During the risk management committee meeting Nicholson evaluates the characteristics ofthe arrangement with Boston Advisors. Nicholson states that the asymmetric nature of Thomasville's contractwith Boston Advisors creates adverse consequences for Thomasville's net profits and that the compensationcontract resembles a put option owned by Boston Advisors.Upon request, Fluellen provides a risk assessment for the firm's large cap growth portfolio using a monthlydollar VAR. To do so, Fluellen obtains the following statistics from the fund manager. The value of the fund is$80 million and has an annual expected return of 14.4%. The annual standard deviation of returns is 21.50%.Assuming a standard normal distribution, 5% of the potential portfolio values are 1.65 standard deviationsbelow the expected return.Thomasville periodically engages in options trading for hedging purposes or when they believe that options aremispriced. One of their positions is a long position in a call option for Moffett Corporation. The option is aEuropean option with a 3-month maturity. The underlying stock price is $27 and the strike price of the option is$25. The option sells for S2.86. Thomasville has also sold a put on the stock of the McNeill Corporation. Theoption is an American option with a 2-month maturity. The underlying stock price is $52 and the strike price ofthe option is $55. The option sells for $3.82. Fluellen assesses the credit risk of these options to Thomasvilleand states that the current credit risk of the Moffett option is $2.86 and the current credit risk of the McNeilloption is $3.82.Thomasville also uses options quite heavily in their Special Strategies Portfolio. This portfolio seeks to exploitmispriced assets using the leverage provided by options contracts. Although this fund has achieved somespectacular returns, it has also produced some rather large losses on days of high market volatility. Nicholsonhas calculated a 5% VAR for the fund at $13.9 million. In most years, the fund has produced losses exceeding$13.9 million in 13 of the 250 trading days in a year, on average. Nicholson is concerned about the accuracy ofthe estimated VAR because when the losses exceed $13.9 million, they are typically much greater than $13.9million.In addition to using options, Thomasville also uses swap contracts for hedging interest rate risk and currencyexposures. Fluellen has been assigned the task of evaluating the credit risk of these contracts. Thecharacteristics of the swap contracts Thomasville uses are shown in Figure 1. Fluellen later is asked to describe credit risk in general to the risk management committee. She states thatcross-default provisions generally protect a creditor because they prevent a debtor from declaring immediatedefault on the obligation owed to the creditor when the debtor defaults on other obligations. Fluellen also statesthat credit risk and credit VAR can be quickly calculated because bond rating firms provide extensive data onthe defaults for investment grade and junk grade corporate debt at reasonable prices.Which of the following best describes the accuracy of the VAR measure calculated for the Special StrategiesPortfolio?
Answer: C
Question 4
Albert Wulf, CFA, is a portfolio manager with Upsala Asset Management, a regional financial services firm thathandles investments for small businesses in Northern Germany. For the most part, Wulf has been handlinglocally concentrated investments in European securities. Due to a lack of expertise in currency management heworks closely with James Bauer, a foreign exchange expert who manages international exposure in some ofUpsala's portfolios. Both individuals are committed to managing portfolio assets within the guidelines of clientinvestment policy statements.To achieve global diversification, Wulf's portfolio invests in securities from developed nations including theUnited States, Japan, and Great Britain. Due to recent currency market turmoil, translation risk has become ahuge concern for Upsala's managers. The U.S. dollar has recently plummeted relative to the euro, while theJapanese yen and British pound have appreciated slightly relative to the euro. Wulf and Bauer meet to discusshedging strategies that will hopefully mitigate some of the concerns regarding future currency fluctuations.Wulf currently has a $1,000,000 investment in a U.S. oil and gas corporation. This position was taken with theexpectation that demand for oil in the U.S. would increase sharply over the short-run. Wulf plans to exit thisposition 125 days from today. In order to hedge the currency exposure to the U.S. dollar, Bauer enters into a90-day U.S. dollar futures contract, expiring in September. Bauer comments to Wulf that this futures contractguarantees that the portfolio will not take any unjustified risk in the volatile dollar.Wulf recently started investing in securities from Japan. He has been particularly interested in the growth oftechnology firms in that country. Wulf decides to make an investment of ¥25,000,000 in a small technologyenterprise that is in need of start-up capital. The spot exchange rate for the Japanese yen at the time of theinvestment is ¥135/€. The expected spot rate in 90 days is ¥132/€. Given the expected appreciation of the yen,Bauer purchases put options that provide insurance against any deprecation of the euro. While delta-hedgingthis position, Bauer discovers that current at-the-money yen put options sell for €1 with a delta of -0.85. Hementions to Wulf that, in general, put options will provide a cheaper alternative to hedging than with futuressince put options are only exercised if the local currency depreciates.The exposure of Wulf’s portfolio to the British pound results from a 180-day pound-denominated investment of£5,000,000. The spot exchange rate for the British pound is £0.78/€. The value of the investment is expected toincrease to £5,100,000 at the end of the 180 day period. Bauer informs Wulf that due to the minimal expectedexchange rate movement, it would be in the best interest of their clients, from a cost-benefit standpoint, tohedge only the principal of this investment.Before entering into currency futures and options contracts, Wulf and Bauer discuss the possibility of alsohedging market risk due to changes in the value of the assets. Bauer suggests that in order to hedge against apossible loss in the value of an asset Wulf should short a given foreign market index. Wulf is interested inexecuting index hedging strategies that are perfectly correlated with foreign investments. Bauer, however,cautions Wulf regarding the increase in trading costs that would result from these additional hedging activities.Regarding the Japanese investment in the technology company, determine the appropriate transaction in putoptions to adjust the current delta hedge, given that the delta changes to -0.92. Assume that each yen putallows the right to self ¥1,000,000.
Answer: A
Question 5
Joan Weaver, CFA and Kim McNally, CFA are analysts for Cardinal Fixed Income Management. Cardinalprovides investment advisory services to pension funds, endowments, and other institutions in the U.S. andCanada. Cardinal recommends positions in investment-grade corporate and government bonds.Cardinal has largely advocated the use of passive approaches to bond investments, where the predominantholding consists of an indexed or enhanced indexed bond portfolio. They are exploring, however, the possibilityof using a greater degree of active management to increase excess returns. The analysts have made thefollowing statements.• Weaver: "An advantage of both enhanced indexing by matching primary risk factors and enhanced indexingby minor risk factor mismatching is that there is the potential for excess returns, but the duration of the portfoliois matched with that of the index, thereby limiting the portion of tracking error resulting from interest rate risk."• McNally: "The use of active management by larger risk factor mismatches typically involves large durationmismatches from the index, in an effort to capitalize on interest rate forecasts."As part of their increased emphasis on active bond management, Cardinal has retained the services of aneconomic consultant to provide expectations input on factors such as interest rate levels, interest rate volatility,and credit spreads. During his presentation, the economist states that he believes long-term interest ratesshould fall over the next year, but that short-term rates should gradually increase. Weaver and McNally arecurrently advising an institutional client that wishes to maintain the duration of its bond portfolio at 6.7. In light ofthe economic forecast, they are considering three portfolios that combine the following three bonds in varyingamounts. Weaver and McNally next examine an investment in a semiannual coupon bond newly issued by the ManixCorporation, a firm with a credit rating of AA by Moody's. The specifics of the bond purchase are providedbelow given Weaver's projections. It is Cardinal's policy that bonds be evaluated for purchase on a total returnbasis.
 One of Cardinal's clients, the Johnson Investment Fund (JIF), has instructed Weaver and McNally torecommend the appropriate debt investment for $125,000,000 in funds. JIF is willing to invest an additional15% of the portfolio using leverage. JIF requires that the portfolio duration not exceed 5.5. Weaverrecommends that JIF invest in bonds with a duration of 5.2. The maximum allowable leverage will be used andthe borrowed funds will have a duration of 0.8. JIF is considering investing in bonds with options and has askedMcNally to provide insight into these investments. McNally makes the following comments:"Due to the increasing sophistication of bond issuers, the amount of bonds with put options is increasing, andthese bonds sell at a discount relative to comparable bullets. Putables are quite attractive when interest ratesrise, but, we should be careful if with them, because valuation models often fail to account for the credit risk ofthe issuer."Another client, Blair Portfolio Managers, has asked Cardinal to provide advice on duration management. Oneyear ago, their portfolio had a market value of $3,010,444 and a dollar duration of $108,000; current figures areprovided below:
 The expected bond equivalent yield for the Manix Bond, using total return analysis, is closest to:
Answer: B
Page: 1
/ 73
Total 365 Questions |
Updated On: Oct 27, 2026
© Copyrights DumpsCertify 2026. All Rights Reserved
We use cookies to ensure your best experience. So we hope you are happy to receive all cookies on the DumpsCertify.