Total 713 Questions |
Updated On: Nov 11, 2026
Start Your Succesful IT Certification Journey With 3 Easy Steps!
1
GET ACCESS / DOWNLOAD
- Get Full Access to Practice Features
- Download Real PDF Questions
- Download Free Demo Version
- Download Free Updated (90 Days)
2
ONLINE PRACTICE
- Free Online IT Exam Practice
- Multiple Questions Sets
- Browser Based Test Engine
- No Installation Required
3
PASS / SUCCESS
- Pass Exam Efficiently
- Achieve A+ Grade
- Guaranteed Success
- Start Brilliant Pro Career
Free CFA Institute CFA-Level-II Exam Questions
Become CFA Institute Certified with updated CFA-Level-II exam questions and correct answers
Page: 1
/ 143
Question 1
James Walker is the Chief Financial Officer for Lothar Corporation, a U .S . mining company that specializes in worldwide exploration for and excavation of precious metals. Lothar Corporation generally tries to maintain a debt-to-capital ratio of approximately 45% and has successfully done so for the past seven years. Due to the time lag between the discovery of an extractable vein of metal and the eventual sale of the excavated material, the company frequently must issue short-term debt to fund its operations. Issuing these one to six month notes sometimes pushes Lothar's debt to capital ratio above their long-term target, but the cash provided from the short-term financing is necessary to complete the majority of the company's mining projects.Walker has estimated that extraction of silver deposits in southern Australia has eight months until project completion. However, funding for the project will run out in approximately six months. In order to cover the funding gap. Walker will have to issue short-term notes with a principal value of $1,275,000 at an unknown future interest rate. To mitigate the interest rate uncertainty, Walker has decided to enter into a forward rate agreement (FRA) based on LIBOR which currently has a term structure as shown in Exhibit 1. Three months after establishing the position in the forward rate agreement, LIBOR interest rates have shifted causing the value of Lothar's FRA . position to change as well. The new LIBOR term structure is shown in Exhibit 2.While Walker is estimating the change in the value of the original FRA position, he receives a memo from the Chief Operating Officer of Lochar Corporation, Maria Steiner, informing him of a major delay in one of the company's South African mining projects. In the memo, Stciner states the following: 'As usual, the project delay will require a short-term loan to cover funding shortage that will accompany the extra time until project completion. I have estimated that in 210 days, we will require a 90-day project loan in the amount of $2,350,000.1 would like you to establish another FRA position, this time with a contract rate of 6.95%.'Walker has decided to enter into a forward rate agreement (FRA). Which of the following is closest to the price of the FRA on the date of the contract's inception?
Answer: B
Question 2
Trent Black is a government fixed-income portfolio manager and on January 1, he holds $30 million of fixed-rate, semi-annual pay notes. Black is considering entering into a 2-year $30 million semi-annual pay interest rate swap as the fixed-rate payer. He must first determine the swap rate. Black notes the following term structure: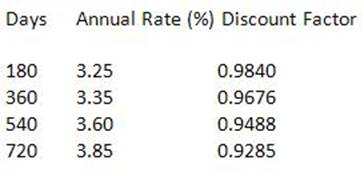 Black is also evaluating receiver and payer swaptions on the same $30 million interest rate swap. The swaptions are European-style swaptions that mature in 240 days. Black anticipates a decline in interest rates and would like to use the swaptions to profit from his interest rate forecast.Black is also concerned about the potential credit risk inherent in both interest rate swaps and swaptions, so he consults Marcus Coleman, a contract specialist in the legal department. Coleman advises Black that:Statement 1: The fixed rate payer in any plain vanilla interest rate swap is exposed to potential credit risk at the initiation of the swap but the floating rate payer is not.Statement 2: The long position is exposed to potential credit risk in a payer swaption at initiation but the shortposition in a payer swaption is not.On May I after 120 days. Black is asked to determine the value of the 2-year, $30 million swap. The term structure after 120 days is:
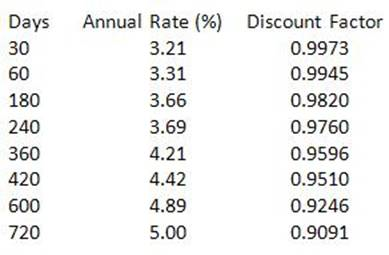 Is Coleman correct with respect to the credit risk of swaps and swaptions?
Answer: C
Question 3
Chris Darin, CFA, works as a sell-side senior analyst and vice president for a large Toronto brokerage firm researching mainly hedge funds and alternative investments. Darin recently hired Simon Nielsen for the position of junior analyst at the firm. Although Nielsen does not have experience evaluating hedge funds, Darin hired him mainly for his previous experience at a discount brokerage firm and for his passion for the industry. Darin frequently mentors Nielsen on market trends, investment styles, and on risks inherent in alternative investment vehicles. In a recent conversation, Darin makes the following statements:Statement 1: One way to measure hedge fund investment performance is through Jensen's alpha. A portfolio with negative Jensen's alpha would plot above the Security Market Line (SML).Statement 2: Both the Sharpe ratio and Jensen's alpha can be used to measure risk-adjusted hedge fund returns. Oneof the advantages is comparability between the two methods since both calculate return relative to systematic risk.Their conversation later shifts to discussing hedge fund classifications and how derivatives affect hedge fund performance measurement. Nielsen mentions that put options are often more advantageous than short selling in a market neutral strategy because of their asymmetric returns.The following week Darin asks Nielsen to research potential problems and biases in hedge fund indexes and general risks inherent in investing in hedge funds. Nielsen compiles the information and presents the following findings:1. One of the data problems in hedge fund indexes is that managers often do not disclose negative fund performance.2. The historical performance of hedge funds that are recently added to an index is often added to the past performance of the index.3. Long/short equity hedge funds are subject to equity market risk. This risk is typically greater than with equity market neutral or risk arbitrage funds due to the higher standard deviations and market correlations inherent in long/short funds.4. Fixed income arbitrage funds are also subject to equity market risk. These funds are short Treasuries and long high-credit-risk bonds. In an economic downturn the short position in Treasuries provides a buffer against the long position and provides a net gain.Finally, the two discuss the risk-free rate and various risk measures in hedge fund performance evaluation. Darin explains that even in market neutral strategies, the risk-free rate may not be an appropriate measure of fund performance. Nielsen does not understand and asks him to clarify. Darin further states that risk measures such as Value at Risk have several limitations as a risk measurement tool.Nielsen's findings on long/short equity funds and fixed income arbitrage strategies, respectively, are:
Answer: C
Question 4
Emily De Jong, CFA, works for Charles & Williams Associates, a medium-sized investment firm operating in the northeastern United States. Emily is responsible for producing financial reports to use as tools to attract new clients. It is now early in 2009, and Emily is reviewing information for O'Connor Textiles and finalizing a report that will be used for an important presentation to a potential investor at the end of the week.Following an acquisition of a major competitor in 1992, O'Connor went public in 1993 and paid its first dividend in 1999. Dividends are paid at the end of the year. After 2008, dividends are expected to grow for three years at 11%: $2.13 in 2009, $2.36 in 2010, and $2.63 in 2011. The average of the arithmetic and compound growth rates are given in Exhibit 1. Dividends are then expected to settle down to a long-term growth rate of 4%. O'Connor's current share price of $70 is expected to rise to $72.92 by the end of the year according to the consensus of analysts' forecasts.O'Connor's annual dividend history is shown in Exhibit 1. De Jong is also considering whether or not she should value O'Connor using a free cash flow model instead of the dividend discount model.
 The output from the regression appears in Exhibit 2.De Jong determines that employing the CAPM to estimate the required return on equity suffers from the following sources of error:* Estimation of the model's inputs (e.g., the market risk premium). The company's dividend payment schedule.* The accuracy of the beta estimate.* Whether or not the model is the appropriate one to use.De Jong observes that two reputable statistical analysis firms estimate betas for O'Connor stock at 0.85 and 1.10. She concludes that the differences between her beta estimate and the published estimates resulted from her use of standard errors in her regression to correct for serial correlation; the other firms did not make a similar adjustment.De Jong considers using adjusted beta in her analysis. Typically, her company uses 1/3 for the value of .
 She determines that her adjusted beta forecast will be closer to the mean reverting level using this value than it would be using a value of 1/3.Is De Jong correct with respect to her conclusions regarding the causes of the differences between her beta estimate for O'Connor and the published beta estimates, and her strategy for adjusting her beta estimate to more quickly approach the mean reverting level of beta?
Answer: B
Question 5
Debbie Angle and Craig Hohlman arc analysts for a large commercial bank, Arbutus National Bank. Arbutus lias extensive dealings in both the spot and forward foreign exchange markets. Angle and Hohlman are providing a refresher course on foreign exchange relations for its traders. Unless indicated otherwise, Angle tells the traders to assume that real interest rates arc equivalent throughout the world.Angle uses a three country example from North America to illustrate foreign exchange parity relations. In it, the Canadian dollar is expected to depreciate relative to the U .S . dollar and the Mexican peso. Nominal, one year interest rates in the United States are 7% and are 13% in Mexico. From this data and using the uncovered interest rate parity relationship, Angle forecasts future spot rates.During their presentation, Hohlman discusses the effect of monetary and fiscal policies on exchange rates. He cites a historical example from the United States, where the Federal Reserve shifted to an expansionary-monetary policy to stimulate economic growth. This shift was largely unanticipated by the financial markets because the markets thought the Federal Reserve was more concerned with inflationary pressures. Hohlman states that the effect of this policy was an increase in economic growth and an increase in inflation. The cumulative effect on the dollar was unchanged, however, because, according to Hohlman, an increase in U .S . economic growth would strengthen the dollar whereas an increase in inflation would weaken the dollar.Regarding U .S . fiscal policies, Hohlman states that if these were unexpectedly expansionary, real interest rates would increase, which would produce an appreciation of the dollar. But, Hohlman adds, an increase in the federal budget would encourage imports such that the overall short-run effect would be for a decrease in the value of the dollar.Using this same historical example, Angle discusses capital flows and the effect on the balance-of-payments components. Angle makes the following statements:Statement 1; Differences in real interest rates will cause a flow of capital into those countries with the highest available real rates of interest. Therefore, there will be an increased demand for those currencies, and they will appreciate relative to the currencies of countries whose available real rates of return are low.Statement 2: The flow of foreign capital into U .S . investments, net of outflows of U .S . capital, is measured by the financial account. In the case of an expansionary fiscal policy, the financial account will increase and move towards a surplus.Angle next discusses the foreign exchange expectation relation. She states that, examining Great Britain and Japan, it appears that the four year forward rate, which is currently 200/, is an accurate predictor of the expected future spot rate. Furthermore, she states that uncovered interest rate parity and relative purchasing power parity hold. In the example for her presentation, she uses the following figures for the two countries. As a follow-up to Angle's example, Hohlman discusses the use and evidence for purchasing power parity. He makes the following statements.Statement 3: Absolute purchasing power parity is based on the law of one price, which states that a good should have the same price throughout the world. Absolute purchasing power parity is not widely used in practice to forecast interest rates.Statement 4: Although relative purchasing power parity is useful as an input for long-run exchange rate forecasts, it is not useful for predicting short-run currency values.Using Angle's analysis, what is the nominal one year interest rate in Canada?
Answer: C
Page: 1
/ 143
Total 713 Questions |
Updated On: Nov 11, 2026
© Copyrights DumpsCertify 2026. All Rights Reserved
We use cookies to ensure your best experience. So we hope you are happy to receive all cookies on the DumpsCertify.